Deck: The IRS treats crypto as property, so selling, trading or spending it can mean a gain or loss to report, and some crypto counts as income. Here's what the IRS says, where it goes on a return, and what's new with Form 1099-DA.
Last reviewed: October 24, 2026
Crypto taxes made me nervous for a long time, mostly because I didn't know what the rules actually said. So I went back to the source: the IRS's own pages. This guide walks through what they say in plain English, with links so you can check every point yourself.
It covers U.S. federal income tax only. It's education, not tax advice. Everyone's situation is different, and a tax professional can apply these rules to yours.
The short version
- Crypto is property for U.S. tax purposes, not currency. Selling it, trading it or spending it can create a capital gain or loss.
- Some crypto counts as income when you receive it, like pay for work, mining rewards and staking rewards.
- Buying with dollars and holding isn't a sale. Neither is moving coins between your own wallets, though a fee paid in crypto is its own transaction.
- Every taxpayer answers a yes-or-no digital asset question on Form 1040.
- Form 1099-DA is new. Brokers report sales made from 2025 on, and from 2026 they also report basis on certain sales.
The core rule: crypto is property
The IRS says it directly: "For U.S. tax purposes, digital assets are considered property, not currency." That one sentence explains most of what follows.
When you dispose of property, you compare what you got for it with what you paid for it. The difference is a capital gain or a capital loss. The IRS also says that if you have digital asset transactions, "you must report them whether or not they result in a taxable gain or loss."
What counts as what
Usually not a sale:
- Buying crypto with dollars and holding it.
- Moving crypto between wallets or accounts you own. The IRS's instructions for the Form 1040 question carve out one wrinkle: paying a transaction fee in crypto is itself a digital asset transaction. Our network fees guide explains those fees.
- Receiving crypto as a gift. Per IRS FAQ 31, you don't have income until you sell or otherwise dispose of it.
Capital gain or loss (you disposed of property):
- Selling crypto for dollars.
- Trading one crypto for another.
- Spending crypto on goods or services.
- Giving crypto to a qualified charity is a special case. Per IRS FAQ 34, you generally don't recognize a gain or loss on the donation.
Ordinary income (you received something of value):
- Crypto paid to you for work or services. IRS FAQ 9 says it's income at its fair market value when received.
- Staking rewards. Revenue Ruling 2023-14 says their fair market value is income "in the taxable year in which the taxpayer gains dominion and control" of them. The IRS also lists a 2026 Tax Court decision (T.C. Memo. 2026-46) holding that staking rewards are income. Our staking guide covers how staking works.
- Mining rewards, and new coins received after a hard fork with an airdrop (Revenue Ruling 2019-24).
How a gain is figured
Your basis is generally what you paid in U.S. dollars. IRS FAQ 8 says that includes "fees, commissions and other acquisition costs." Your gain or loss is what you received minus your basis.
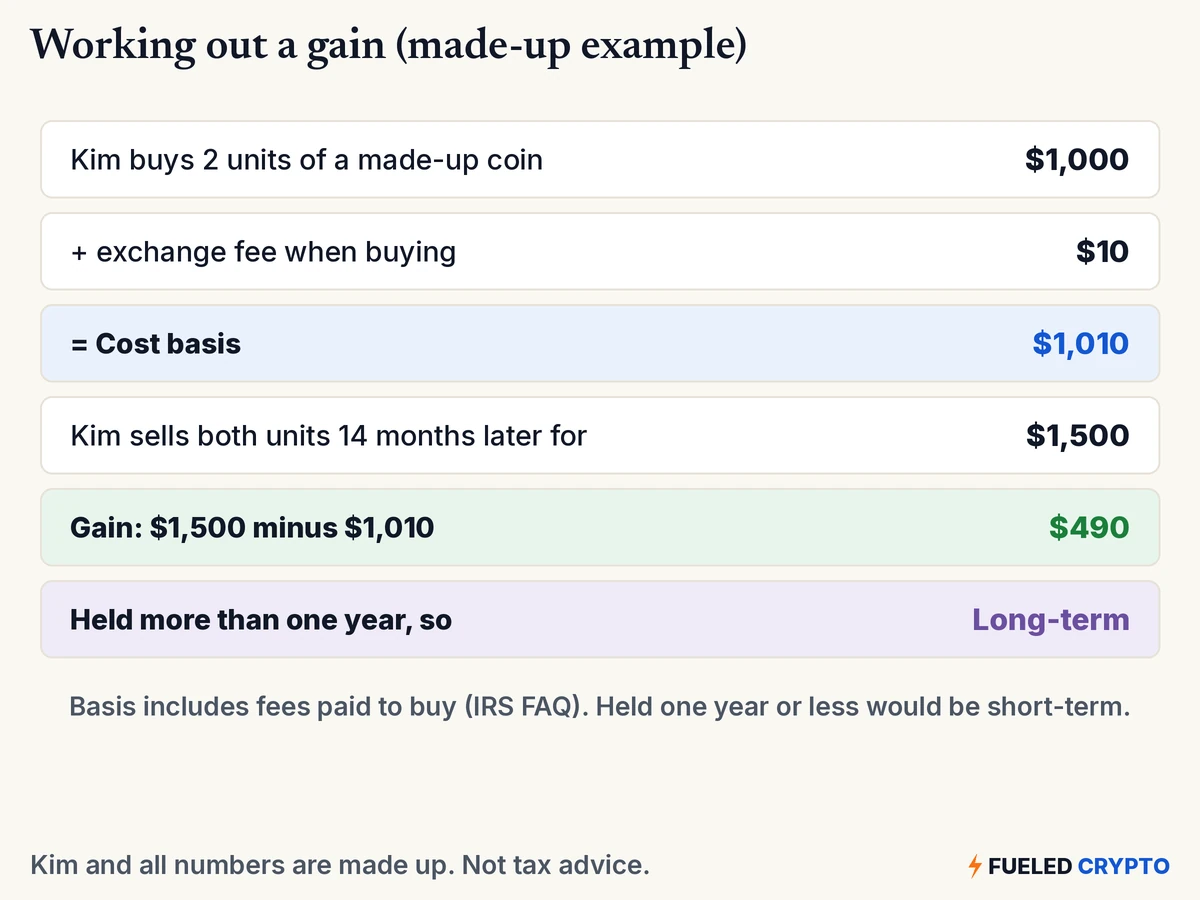
How long you held it matters:
- One year or less: short-term. Taxed at ordinary income rates.
- More than one year: long-term. Taxed at 0%, 15% or 20%, depending on taxable income.
For tax year 2026 (returns filed in 2027), the IRS's inflation figures in Revenue Procedure 2025-32 set the long-term thresholds like this:
| Filing status | 0% rate up to | 15% rate up to | 20% rate |
|---|---|---|---|
| Single | $49,450 | $545,500 | Above that |
| Married filing jointly | $98,900 | $613,700 | Above that |
| Head of household | $66,200 | $579,600 | Above that |
| Married filing separately | $49,450 | $306,850 | Above that |
For tax year 2025, IRS Topic 409 lists the 0% threshold as $48,350 for single filers and $96,700 for married couples filing jointly. Other rules can apply, so Topic 409 is the place to check the details.
Losses. If your capital losses are bigger than your gains, Topic 409 says you can deduct the lesser of $3,000 ($1,500 if married filing separately) or your net loss, and carry the rest forward to later years.
Which units did you sell? If you bought the same coin at different times and prices, the IRS FAQs (39 and 40) let you choose specific units if you can identify them with records. If you don't, the IRS treats the first units you got as the first ones sold (first in, first out).
Where it goes on a return
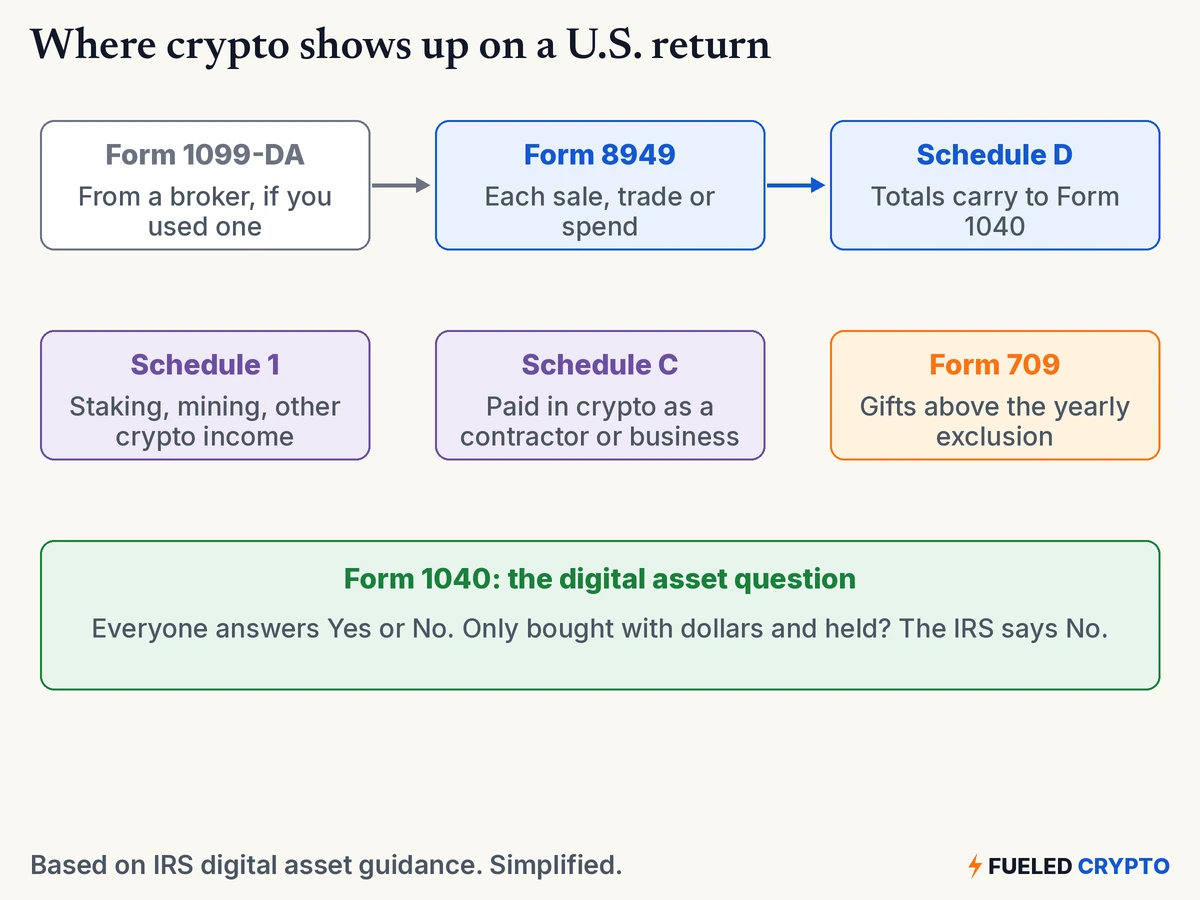
According to the IRS Digital Assets page:
- Form 8949 lists each capital sale, trade or spend. Totals carry to Schedule D.
- Schedule 1 is for income from forks, staking, mining and similar.
- Schedule C is for crypto received as an independent contractor or in a business.
- Form 709 is the gift tax return. A giver may need to file it when gifts to one person in a year go above the annual exclusion, which is $19,000 for 2026 (IR-2025-103).
The question everyone answers. Form 1040 asks whether, at any time during the year, you "(a) receive (as a reward, award or payment for property or services); or (b) sell, exchange, or otherwise dispose of a digital asset (or a financial interest in a digital asset)." The IRS says to answer "No" if you only held crypto, only bought it with real currency, or only moved it between your own wallets, unless you paid a transaction fee in crypto.
What's new: Form 1099-DA
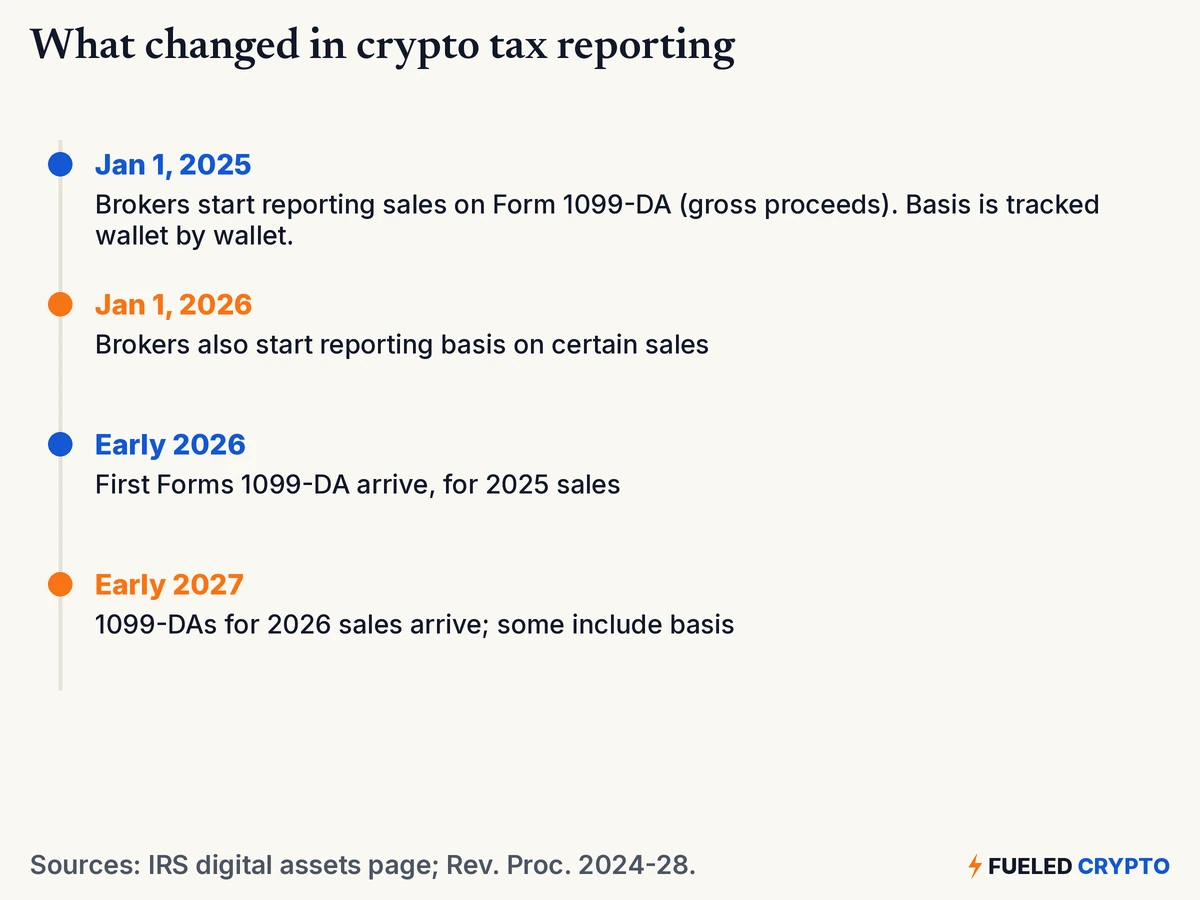
The IRS Digital Assets page says: "Brokers must report gross proceeds for transactions effected on or after Jan. 1, 2025. Brokers must report basis on certain transactions effected on or after Jan. 1, 2026." The rules don't cover non-custodial brokers, so activity in a self-custody wallet may not show up on any 1099-DA.
A few things that follow from that:
- A 1099-DA for 2025 may show what you sold for, but not what you paid. The basis still has to come from your own records.
- Basis is now tracked wallet by wallet. Revenue Procedure 2024-28 gave a way to assign unused basis to each wallet or account as of January 1, 2025.
- You report crypto even without a form. IRS FAQ 42 says to report "regardless of the amount or whether you receive a payee statement."
Keeping records
The IRS FAQs expect you to be able to show what you bought, when, for how much, and what you got when you disposed of it. In practice that means keeping:
- Dates you acquired and disposed of each asset.
- What you paid and what you received, in U.S. dollars.
- Fees, and which wallet or account each asset sat in.
- Exports of your transaction history from each platform you use, saved somewhere you control. Our blockchain explorer guide shows how to look up on-chain transfers.
Some people keep this in a spreadsheet. Common options also include crypto tax software or working with a tax professional.
Rules people often ask about
Wash sales. The wash-sale rule in 26 U.S.C. § 1091 applies to "shares of stock or securities." As of October 24, 2026, Congress hasn't extended it to digital assets. Bills to do that are pending: H.R. 9172 (introduced June 8, 2026) and H.R. 10357, the Digital Asset Tax Certainty Act, which the House Ways and Means Committee approved 38–5 on September 16, 2026. Neither is law. Check the current rules before relying on this.
Foreign accounts (FBAR). FinCEN Notice 2020-2 says that "at this time, a foreign account holding virtual currency is not reportable on the FBAR" unless it also holds other reportable assets. FinCEN said it intends to propose changing that. Other foreign-asset reporting rules may still apply, which is a good question for a tax professional.
Losses on a failed platform. How these are treated depends on the facts and the type of loss. It's an area where a tax professional's help really matters.
Common mix-ups
- "Crypto-to-crypto trades aren't taxable." The IRS treats a trade as disposing of property, which can create a gain or loss.
- "No 1099, nothing to report." IRS FAQ 42 says to report regardless of whether you get a payee statement.
- "I only moved coins between my wallets, so I answer Yes." The IRS says that alone is a "No," unless you paid a fee in crypto.
- "Gifts over $19,000 mean the gift is taxed." Going over the annual exclusion can mean the giver files Form 709. It doesn't by itself mean the recipient has income.
- "Staking rewards are only taxed when sold." Revenue Ruling 2023-14 says they're income when you gain control of them.
Words you'll keep hearing
- Basis (cost basis): what you paid, in U.S. dollars, including acquisition fees.
- Capital gain or loss: what you received minus your basis when you dispose of property.
- Short-term / long-term: held one year or less / more than one year.
- Fair market value: the dollar value of crypto at the moment you receive or dispose of it.
- Form 1099-DA: the form brokers use to report digital asset sales to you and the IRS.
- Specific identification: choosing which units you sold, backed by records.
- Annual exclusion: the amount you can give one person in a year before a gift tax return may be needed ($19,000 for 2026).
More terms are in our crypto glossary.
Frequently asked questions
Do I owe tax if I just bought crypto and held it? Buying with dollars and holding isn't a sale. The IRS says you can answer "No" to the Form 1040 digital asset question if that's all you did, unless you paid a transaction fee in crypto.
Is trading one crypto for another taxable? The IRS treats crypto as property, so a trade is a disposal that can create a capital gain or loss to report on Form 8949.
Are staking rewards taxable? Revenue Ruling 2023-14 says the fair market value of staking rewards is income in the year you gain dominion and control of them. Selling them later is a separate event with its own gain or loss.
What is Form 1099-DA? It's the form brokers use to report digital asset sales. Gross proceeds are reported for sales on or after January 1, 2025, and basis for certain sales on or after January 1, 2026.
Do I have to report crypto if I didn't get a 1099? Yes. IRS FAQ 42 says to report "regardless of the amount or whether you receive a payee statement."
Does the wash-sale rule apply to crypto? As of October 24, 2026, the rule in 26 U.S.C. § 1091 covers stock and securities, and bills to extend it to digital assets are pending in Congress. Check the current rules before relying on this.
Can I deduct crypto losses? Capital losses offset capital gains. If losses are bigger, IRS Topic 409 says you can deduct up to $3,000 a year ($1,500 if married filing separately) and carry the rest forward.
Where to go next
- How Crypto Transactions Work, for what happens when you send or trade.
- Crypto Network Fees, Explained, for the fees mentioned above.
- What Is Staking?, for how staking rewards are earned.
- Crypto Estate Planning, for gifts, inheritance and planning ahead.
- Crypto IRAs Compared, for how tax-advantaged accounts work.
- Crypto Glossary, for any other term.
Sources
- IRS: Digital assets (page last updated September 2, 2026; property treatment, the Form 1040 question, forms, Form 1099-DA, Rev. Proc. 2024-28 and the guidance list including T.C. Memo. 2026-46).
- IRS: Frequently asked questions on virtual currency transactions (FAQs 8, 9, 31, 34, 39, 40 and 42).
- IRS: Revenue Ruling 2023-14 (staking rewards).
- IRS: Revenue Ruling 2019-24 (hard forks and airdrops).
- IRS: Topic no. 409, Capital gains and losses.
- IRS: Revenue Procedure 2025-32 (2026 inflation-adjusted figures).
- IRS: IR-2025-103, tax inflation adjustments for tax year 2026 (October 9, 2025; $19,000 annual gift exclusion).
- Cornell Law School, Legal Information Institute: 26 U.S.C. § 1091, wash sales.
- Congress.gov: H.R. 9172 (introduced June 8, 2026).
- EY Tax News: Ways and Means approves digital assets tax bill (H.R. 10357; September 16, 2026 markup).
- FinCEN: Notice 2020-2, virtual currency reporting on the FBAR (December 30, 2020).
All diagrams and animations are original Fueled Crypto graphics. Kim is a made-up example.
Fueled Crypto publishes news and education, not investment, tax, or legal advice. Crypto assets are volatile and can lose value. Do your own research and consider a licensed professional before making financial decisions. See our full disclaimer.
Want plain-English crypto news once a week? Subscribe to Fueled Crypto.